OVERVIEW OF PAPER AND PULP INDUSTRY AT THE FIRST HALF OF 2023 AND TRENDS FOR THE SECOND HALF OF THE YEAR
Vietnam’s paper and pulp industry in the first months of 2023 is facing difficulties because production and consumption output both decreased significantly compared to the same period last year. The current difficult situation forces the industry to take actions to revive and recover in the last months of the year.
I. Overview of paper and pulp industry at the beginning of 2023
1. Paper production Serial
a. Material 1: Pulp
The current paper and pulp industry in Vietnam still depends mainly on the supply of imported pulp. The amount of pulp produced domestically is still quite limited, not enough to meet the supply. According to VIRAC’s report, the output of domestic pulp enterprises, which mainly produce bleached pulp from hardwood, only meets about 35% of the demand for pulp for domestic paper production. The remaining 65% has to depend on the supply of imported pulp, mainly from North America and Latin America.

Source: VIRAC’s Report
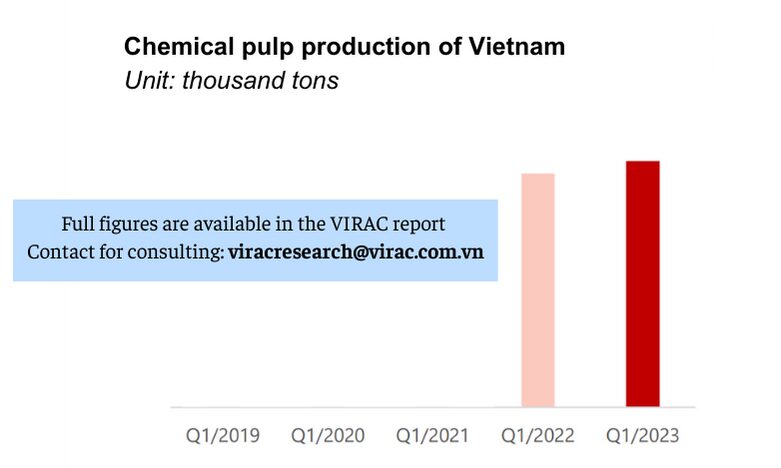
According to VIRAC’s report, in the first quarter of 2023, pulp production is estimated at about 42 thousand tons, up more than 5% over the same period.
The reason is attributed to the fact that demand from paper mills in the first quarter of this year recovered and increased more strongly than the same period last year.
Secondly, because factories are no longer experiencing labor shortages like in 2021-2022, operating capacity is being operated again at optimal levels.
In addition, the supply chain of pulp materials is also being restored thanks to the growth in logistics and the open-door policy from countries after COVID.
Source: VIRAC’s Report
Besides, also according to VIRAC’s report, Vietnam’s pulp import volume in Q1/2023 is estimated at about 78,000 tons, up about 5.5% over the same period last year.

Source: VIRAC’s Report
It can be seen that, in the current situation, Vietnam has to import a lot of wood pulp, affecting the cost of raw materials for wood production in Vietnam.
The question is, why do we still have a large amount of wood chips and wood chips (the main raw material for pulp production) but cannot be used to the maximum in the country and still have to pay import costs. In response to this issue, experts of paper and pulp industry leaders gave an explanation:
- First, the access to raw materials is having a big problem. The current small supply also makes it difficult to access. Although every year Vietnam exports more than 15 million tons of wood chips, the supply is scattered and spontaneous, there is no large enough material area to build a pulp factory. In order to have a factory located in a large and stable raw material area, enterprises need to own forests for paper production.
- Second is the problem of capital difficulty. Building a pulp factory will require a huge amount of capital with a long payback period.
- The third issue is about the state’s policy mechanism. Currently, the State does not have mechanisms and policies to develop large raw material areas. Currently, state-owned forestry enterprises are allocating land to each household. Therefore, it is very difficult to negotiate the source of raw materials with each individual and each household, even though some enterprises have tried to implement it.
b. Material 2: Revocation paper
Besides pulp, recovered paper is also an indispensable source of raw materials for the paper and pulp industry in developed and industrialized countries. This is the second source of fiber materials of the paper and pulp industry, this material does not come from forest trees but is collected from used paper sources.
Recovered paper has very high practical significance, especially for countries with high population and high demand for paper.

Source: VIRAC’s Report
According to VIRAC’s report, in the first quarter of 2023, Vietnam’s imported volume of recovered paper is estimated at about 1 million tons. In which, the US, Europe and Japan are important import partners of Vietnam’s recovered paper, with the proportion of imports coming from these markets accounting for about 75%.
2. Paper production situation in the first months of the year
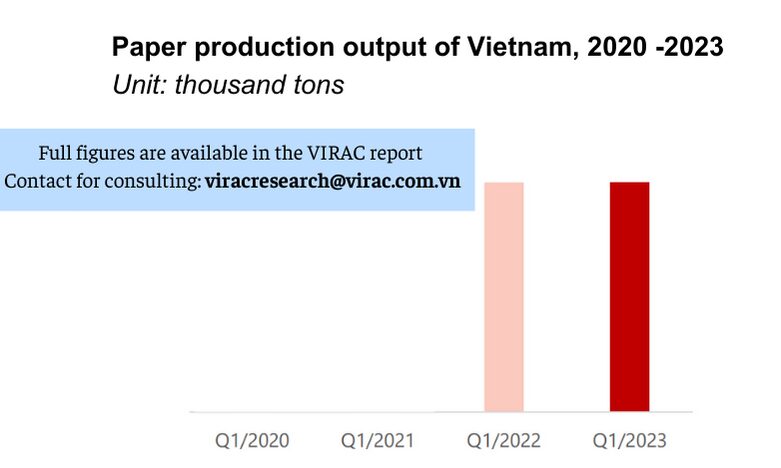
According to VIRAC, Vietnam’s paper production output in the first quarter of 2023 is estimated at about 1.4 million tons, down slightly by 0.01% over the same period in 2022.
Source: VIRAC’s Report
However, in April, the production situation decreased sharply, causing the total paper production in the first 4 months of the year to decrease by more than 12% compared to the same period last year.

Source: VIRAC’s Report
According to Virac’s report, in the first quarter of 2023, paper consumption in Vietnam was estimated at 1.2 million tons, down more than 20% compared to the same period in 2022. In particular, packaging paper is considered the driving force for increasing Head of paper and pulp industry.
However, in the first quarter of 2023, packaging paper consumption was estimated at about 900 thousand tons, down more than 26% compared to the same period in 2022.
It can be seen from the above figures, 2023 is a difficult year for paper enterprises under the impact of the supply situation far beyond demand, consumption demand sharply decreased.
In fact, paper and pulp industry is currently the main industry for the production of most areas, so recently when the production industries have been reduced, it has led to a decline in paper consumption. Up to 90% of domestic paper production is the common packaging paper products for industrial manufacturing industries. During the time from September 2022, paper enterprises were very difficult due to the decline in order.
According to the general report, the difficult market also strongly affects the revenue and profit of paper enterprises.
For example, at Ben Tre Dong Hai Joint Stock Company, the revenue of the first quarter of 2023 reached 848.4 billion dong, down nearly 18% compared to the same period in 2022. Or Hapaco Group Joint Stock Company also recorded revenue In the first quarter of 74.5 billion, a sharp decrease of 45.2% compared to the same period in 2022. And Sadico Can Tho Joint Stock Company, Quarter 1/2023, revenue reached 255.8 billion dong, also reduced to 34 , 5% compared to the same period in 2022. Find out more about the business here.
The consumption of the paper industry is slowing down, while the excess capacity has been posing many major challenges for businesses in the industry.

Source: VIRAC’s Report
All paper products such as printing paper, writing paper, non -coated packaging paper, tissue paper, votive paper have increased export output in the first 3 months of this year. This has contributed to the export turnover of paper and paper products in the first quarter achieved a growth rate of 12.3% compared to the same period 2022 ..
However, in April, the export turnover suddenly dropped sharply, the total export of all kinds decreased by 14.8% compared to the same period last year, of which packaging paper decreased by 19.6%. The demand decreases, while businesses still try to maintain the production and accept inventory to keep workers. This situation is expected to last until the end of 2023 and maybe longer.
II. Forecast of paper and pulp industry situation in the last half of the 2023
This 2023 is expected to be a difficult year for paper and pulp industry under the impact of the supply far beyond the demand while the demand is sharply decreasing.
-
Paper and pulp industry faces many challenges in the early stages of 2023
The paper and pulp industry is facing many challenges in 2023 when in the end of 2022, some businesses have to produce moderately.
Regarding the issue of value added tax of paper enterprises is also facing barriers, because most of the raw materials purchased from the bottle collector, so it is difficult to prove the origin of goods … From here, the cost will be affected. This is also a big barrier for businesses in the paper and pulp industry in effectively controlling the company’s financial plan.
In addition, the import of raw materials for chemical pulp is expected to be difficult at the strong fluctuations of the exchange rate; the shortage of containers, freights and some other costs such as fuel, energy, supplies, chemicals are expected to also negatively impact on the price of the product.
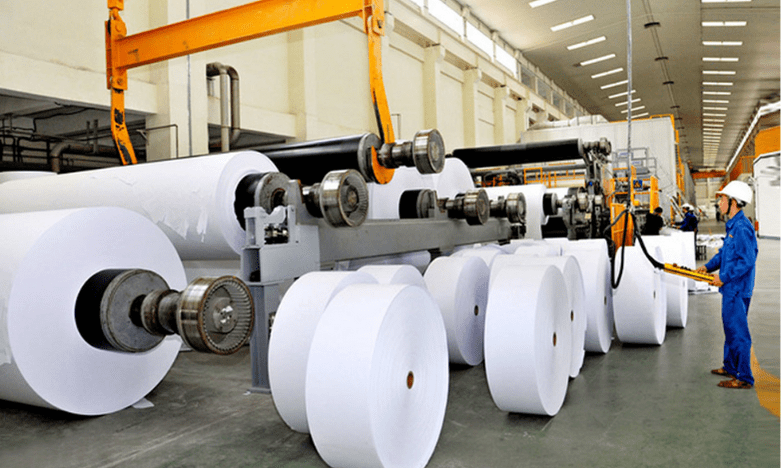
According to the Paper and Pulp Association (VPPA), the paper and pulp industry is still facing great difficulties, which is a decrease in export, but the factory still has to maintain operations to retain workers. This is a situation of excess labor source that wastes costs for each enterprise in paper and pulp industry.
It is expected that the difficulty of the paper and pulp industry will last until the end of this year and maybe longer because the world economic situation is in a state of recession and reduced demand. The opportunity to recover is only when the manufacturing industries begin to restore orders, paper enterprises have the opportunity to revive, “cross the bottom”.
2. Forecast of packaging paper consumption and export
In 2023, the demand for domestic and export packaging paper is expected to continue to grow, but the future growth is expected to be lower than that of 2022 due to being affected by many weaknesses. Unpredictable risk fluctuations may take place.
- The industry uses many packaging paper such as agricultural, forestry, fisheries and processing industrial goods groups (textiles; footwear; wooden furniture; phones of all kinds and components; Low aperture in 2023 due to inflation effects in export markets.
- The export of packaging paper to Vietnam’s main market is currently the Chinese market. In 2023, the prospect of growth was higher than 2022 because China’s packaging demand was expected to increase sharply when the economy reopened.
- In the long term, the packaging paper and pulp industry in the world and Asia is expected to grow slightly. The restriction of plastic waste in the world is gradually disseminating, especially in large economies in the period of 2022 – 2025 by sustainable trend, towards the environment, using paper packaging instead of plastic waste. And plastic bags are growing at all ages, especially young people.
Information on Vietnam paper and pulp industry is compiled from the “Vietnam Paper And Pulp Industry Report in Q1/2023” conducted by VIRAC. The report provides full information on the macroeconomics, trade supply and demand of the accommodation service, relevant information and forecasts from the latest updated data.
REGISTER FOR PAPER AND PULP INDUSTRY REPORT
VIRAC can conduct customized research and reporting to meet the special and in-depth needs of customers. Register for topics HERE.
VIRAC provides more than 20 economic sectors such as Real Estate, Paper And Pulp, Footwear Leather, Oil and Gas, Textile and Garment, Electricity, Beverage, Pharmaceuticals, Wood, Aviation, Chemicals, Macro Economy, Electronic Components, Logistics, Accommodation, Plastics, Automobile, Coal, Steel, Animal Feed, Food, Construction Materials, Minerals, Telecommunications and Cement…
Contact us for the fastest consultation:
Email: viracresearch@virac.com.vn
VIRAC was established by a reputable team of personnel with expertise in information, finance, and market research in the region. VIRAC specializes in providing products and services related to:
- Industry research
- Company research
- Market research
- VIRACE data platform
VIRAC’s partners:
- Joint Stock Commercial Bank for Foreign Trade of Vietnam (Vietcombank)
- Vietnam Joint Stock Commercial Bank for Industry and Trade (Vietinbank)
- Vietnam Bank for Agriculture and Rural Development (Agribank)
- Military Commercial Joint Stock Bank (MB Bank)
- Unilever Vietnam International Company Limited
- Olam International
- FrieslandCampina